Retiring in Malaysia: the Practical 2026 Guide (Real Costs, Visa, Healthcare, Housing)
Key facts
What retirement in Malaysia really costs in 2026: monthly budget by city, MM2H and visa alternatives, health insurance for retirees, rent or buy, territorial taxation and the first six months' settling-in sequence.
Retiring in Malaysia: the practical 2026 guide (real costs, visa, healthcare, housing)
Retiring in Malaysia is no longer an eccentric idea: it is a considered project for thousands of Europeans looking for a tropical climate, controlled living costs and a good private healthcare system. But between the brochures of Kuala Lumpur estate agents and Malaysian administrative reality, the gap is sometimes brutal. The visa is not granted in three clicks, health insurance costs more than advertised, and long-term rentals follow their own rules.
This guide treats the subject as a preparation file, not a sales pitch: how much a retirement in Malaysia really costs in 2026, which visa to choose between MM2H and long-stay alternatives, how healthcare works, where to settle depending on your profile (Kuala Lumpur, Penang, Johor Bahru, Ipoh, Langkawi), and which mistakes to avoid in the first six months. All price ranges are in Malaysian ringgit (MYR) and reflect field observations, not developer promises.
If you are at the very start of the project, begin with our expat guide and our article moving to Malaysia, which cover the general logistics of the move.
How much does retirement in Malaysia really cost in 2026?
Malaysia's cost of living remains a major argument, but you must distinguish three levels of comfort. Here are realistic monthly ranges for a retired couple, housing included, excluding international travel and excluding the health insurance premium (covered below).
| Item | Economical (Ipoh, Alor Setar) | Comfortable (Penang, Johor Bahru) | High end (KL centre, Mont Kiara) |
|---|---|---|---|
| 2-bed furnished rent | MYR 1,500 – 2,200 | MYR 2,500 – 3,800 | MYR 4,500 – 7,000 |
| Food (groceries + eating out) | MYR 1,200 – 1,600 | MYR 1,800 – 2,400 | MYR 2,800 – 4,000 |
| Electricity, water, internet | MYR 250 – 400 | MYR 350 – 550 | MYR 550 – 900 |
| Transport (car + fuel) | MYR 400 – 600 | MYR 500 – 700 | MYR 600 – 900 |
| Miscellaneous, leisure | MYR 500 – 800 | MYR 800 – 1,200 | MYR 1,500 – 2,500 |
| Total (excl. health) | ≈ MYR 3,850 – 5,600 | ≈ MYR 5,950 – 8,650 | ≈ MYR 9,950 – 15,300 |
For a single person, count roughly 70% of these amounts; the difference is mostly housing. Our cost of living page breaks it down item by item, city by city.
Three important remarks:
- Rent decides everything. A decent two-bedroom in Mont Kiara costs two to three times an equivalent home in Ipoh or Alor Setar. Many retirees start in Kuala Lumpur then move to Penang or Ipoh after a year.
- Food can stay very cheap if you eat local: a dish in a hawker centre costs MYR 8-15, a kopitiam MYR 5-10. Imported supermarkets (European products, cheese, wine) blow up the budget.
- Electricity has risen with the subsidy reform. An air-conditioned home in Kuala Lumpur can exceed MYR 600 per month in the hot season.
Malaysia sits above rural Thailand and Vietnam, and well below Singapore.
Which visa for a retiree? MM2H and alternatives
The visa is the most structuring decision of the project: it determines length of stay, property purchase rights and access to bank accounts.
MM2H (Malaysia My Second Home)
This is the historic scheme, restructured into three tiers (Silver, Gold, Platinum), with fixed-deposit and income requirements increasing with the tier. MM2H gives a renewable long-term pass, multiple entries and, depending on the tier, property purchase rights above a threshold.
What to know before applying:
- The fixed deposit is locked in a Malaysian bank for a set period; part of it can later be withdrawn for property purchase or medical expenses. It is not money lost, but it is tied-up cash.
- Minimum physical presence and declaration obligations are verified. A vague file is rejected.
- Processing times depend on the centre and file quality: expect several months, not weeks.
Tier details, amounts and documents are in our MM2H 2026 guide and our article MM2H Malaysia 2026.
Other possible routes
- Renewing 90-day tourist stays: some retirees do it. It is not recommended — a fragile practice that can lead to refusal of entry and gives no access to bank accounts or long leases.
- Employment Pass or Residence Pass-Talent: for people still working, including senior consulting. See Employment Pass.
- DE Rantau Nomad Pass: if you have a remote consulting activity, this can bridge until full retirement. See DE Rantau.
- Spouse and dependant visas: Dependant Pass (DP) allows joining the main pass holder. See Dependant Pass.
Our recommendation: if you are retired with stable income (pension, dividends, foreign rental income), aim for MM2H. It is the most durable scheme and the one that opens the most practical doors. For procedures common to all visas, see visas and immigration.
Healthcare: the critical budget line
Malaysia has private hospitals of international standard (Kuala Lumpur, Penang, Subang Jaya, Johor Bahru) and a public network that is very accessible to nationals. Foreigners do not benefit from public reimbursement: they pay privately, either directly in a private hospital or as paying patients in a public one.
Practical consequences:
- International health insurance is essential. For a retired couple aged 60-65, expect premiums of several thousand ringgit per year per person, depending on age, history and coverage level. Premiums rise with age: plan a growing budget, not a fixed rate.
- Pre-existing conditions are excluded if you subscribe after arriving. Subscribing before departure is often the only way to have them covered, on conditions worth checking.
- Everyday care remains affordable: a GP consultation in a private clinic costs MYR 80-180, a full blood panel MYR 300-700. Far below European prices, which is what drives medical tourism in Penang.
- Medical evacuations to Singapore or Europe are expensive: check your policy covers them.
Our health page and our article expat health insurance detail contracts and pitfalls. Our article on the Malaysian healthcare system explains public/private organisation. Subscription and dependant registration go through the health and life insurance procedure.
Where to settle: five profiles, five cities
The city matters more than the visa for day-to-day quality of life.
Kuala Lumpur: urban comfort at a price
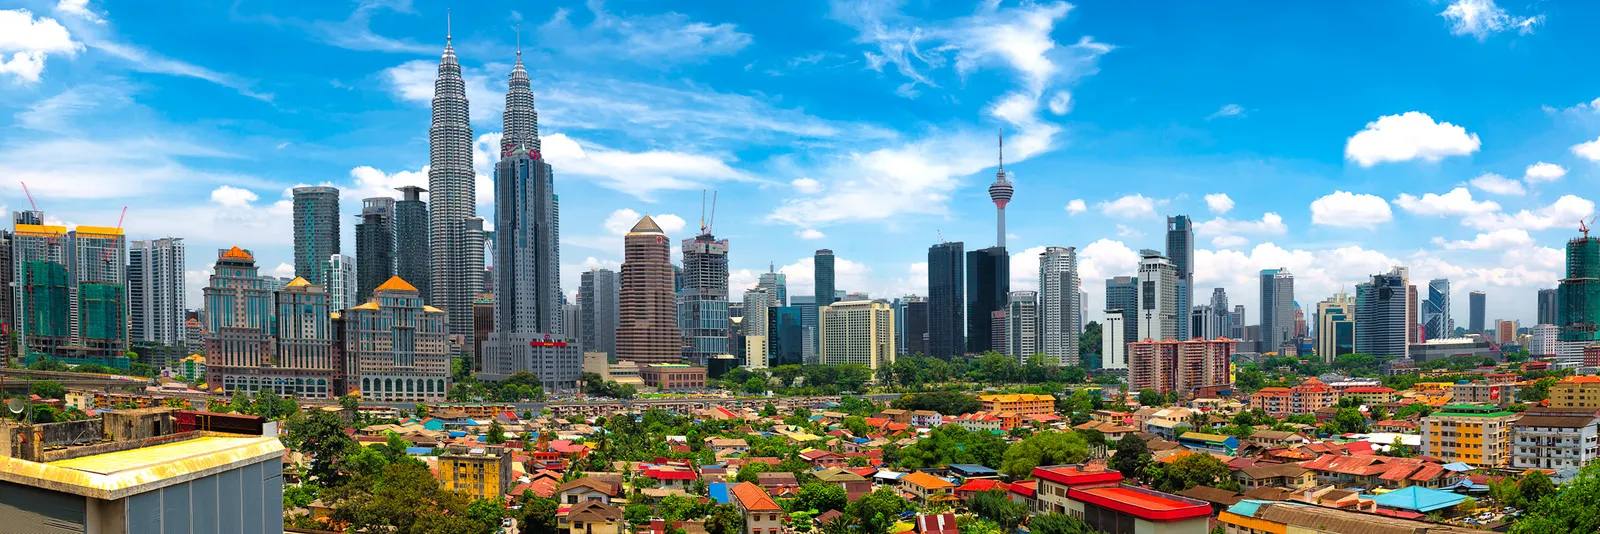
Top private hospitals, international restaurants, a major airport, public transport, a large expat community. The default choice for retirees who want dense urban life and accessible care. Neighbourhoods to consider: Mont Kiara, Bangsar, Desa ParkCity, KLCC. Our article where to live in Kuala Lumpur compares districts and rents, and our accommodation page gives contractual markers.
Penang (George Town): culture, food, sea
The most often praised compromise: historic city, exceptional food scene, reputable private hospitals (notably cardiology), sea 20 minutes away. Rents are lower than Kuala Lumpur for the same surface. The downside: George Town traffic and humidity.
Johor Bahru: next to Singapore
Ideal if you want to stay close to an international hub: 30-60 minutes from Singapore depending on the checkpoint, Malaysian costs, long-haul flights via Changi. Watch out for daily border jams.
Ipoh and Alor Setar: the minimal budget
Secondary cities, calmer, with decent but not cutting-edge private hospitals. This is where the monthly budget goes lowest. Ipoh appeals for its heritage and food; Alor Setar is more rural and closer to Langkawi.
Langkawi: the island, with constraints
Beautiful setting, attractive local rules on some properties, but limited medical offer: serious emergencies mean a flight to Penang or Kuala Lumpur. Best for healthy retirees with insurance including evacuation.
Our destinations page describes each city and its surroundings, and our article Langkawi gives an overview of the island.
Housing: rent or buy?
Rent
The default choice for newcomers, and the right one: it lets you test a neighbourhood before committing.
- Security deposit: typically 2 months' rent, plus 1 month advance.
- Agency commission: often 1 month's rent (paid by the tenant for a 2-year lease).
- Standard term: 1 to 2 years, with renewal and rent review clauses.
- Furnished or unfurnished: both exist; furnished costs 10-25% more but avoids a large upfront investment.
Negotiate the annual review before signing. Many landlords ask for an increase at renewal; a capped clause protects you.
Buy
Purchase by a foreigner is possible but regulated:
- Minimum price thresholds per state: they vary and have been raised in recent years, effectively excluding the entry segment.
- Higher stamp duty for non-citizens, plus registration fees.
- Restrictions on land classified as Malay Reserve and on certain property types.
- Local financing (Malaysian bank loan) is possible but conditions depend on the visa and documented income.
Our article buying property in Malaysia details thresholds, taxes and the process. Never sign a preliminary agreement without a local lawyer checking the land title.
The first six months: the sequence that avoids mistakes
- Arrive with the visa validated, not as a tourist hoping to regularise on site. Changing status from inside the country is rarely possible.
- Open a local bank account as soon as the visa is in hand: it is the key to paying rent, bills and topping up e-wallets. See our article opening a bank account and the opening a bank account procedure.
- Take out health insurance immediately, before any medical issue.
- Rent short-term for one to three months, time to visit neighbourhoods on site.
- Convert your driving licence if you plan to buy a car. See our article driving in Malaysia and the licence conversion procedure.
- Register with your embassy: useful for a lost passport or an emergency. See registering with your embassy.
- Get a local SIM card for online procedures (banking, e-wallets, appointments). See the SIM card procedure.
One often-forgotten point: official documents sometimes require certified translation into English or Malay. Have birth certificates, marriage certificates and pension statements translated before departure; it saves weeks of delay.
Tax and retirement: what to anticipate
Malaysia applies a territorial regime: foreign-sourced income is, in principle, not taxed for a resident, subject to exemption and declaration rules. Foreign pensions and investment income are therefore generally outside Malaysian tax — but this deserves case-by-case validation, as the rules on declaring foreign income have evolved.
However:
- Malaysian-sourced income is taxable (rent from property located in Malaysia, local interest, activity carried out locally).
- Tax residence is determined notably by days of presence (more than 182 days in the calendar year).
- Your home country may still tax you under its own law and the tax treaty with Malaysia.
We do not give personalised tax advice: consult a Malaysian accountant and, if needed, a tax adviser in your country of nationality before departure. Our article what changes for expats in 2026 reviews recent developments.
FAQ
What monthly budget for a retired couple in Malaysia?
MYR 4,000 to 5,600 in a secondary city such as Ipoh, MYR 6,000 to 8,700 in Penang or Johor Bahru, and MYR 10,000 to 15,000 for high-end comfort in Kuala Lumpur. These amounts include housing but exclude health insurance and international travel.
Do I need MM2H or can I stay as a tourist?
MM2H is the recommended route: it gives stable status, access to bank accounts and long leases. Living by renewing 90-day stays is fragile and can lead to refusal of entry. See our MM2H guide.
Can a retired foreigner buy property in Malaysia?
Yes, above the minimum price threshold set by each state, with higher stamp duty for non-citizens. Have the land title checked by a local lawyer before any payment. See our article buying in Malaysia.
Is health insurance really necessary?
Yes. Foreigners get no public reimbursement and private hospitalisation can cost tens of thousands of ringgit. Subscribe before departure to cover pre-existing conditions.
Is foreign income taxed in Malaysia?
In principle not, under the territorial regime, but exemption and declaration rules must be checked case by case. Malaysian-sourced income, however, is taxable.
📋 Related procedures
- Visas and immigration
- Health and life insurance
- Opening a bank account
- Driving in Malaysia
- Registering with your embassy
👉 Preparing your retirement in Malaysia? Contact us for help with the MM2H visa, housing and settling-in steps — or read our expat guide.
Ready to explore Malaysia?
Book your transfer, plan your trips and find the right contacts.
You may also like
MM2H 2026: Requirements, Tiers and Costs of Malaysia's Long-Stay Visa
MM2H 2026 explained: the four categories (Silver, Gold, Platinum, SEZ/SFZ), fixed deposits, compulsory property purchase, minimum stay, real fees, tax treatment, health insurance and the full application process.
The Malaysian Healthcare System in 2026: Hospitals, Costs and Insurance for Expats
How does Malaysia's healthcare system work? Public and private hospitals in Kuala Lumpur, treatment costs, compulsory insurance and emergencies: the complete 2026 guide for expats.
Malaysia Visa 2026: Complete Guide (Types, Costs & How to Apply)
Malaysia Visa 2026: visa-free entry for 60+ countries, mandatory MDAC, Employment Pass, MM2H, DE Rantau. All visa types, costs and application steps.